Paul Hillary, mortgage broker at Coast 2 Coast Property Finance, at his desk in Bondi Junction.
Your situation. Your goals. Your next move.
I understand the story behind the numbers.
I'm Paul Hillary, a mortgage broker based in Bondi Junction. I take the time to understand where you are today, what you want to achieve and what matters most to you. Then I go and find the lending that fits.
Whether your circumstances are straightforward or anything but, I explore the options available and work with you, with lenders and with your other advisers to find a way forward.
No cost to you for my service in most cases. No obligation, no paperwork before we've spoken.
- 17 years in property and finance
- A broad panel of lenders through my network
- Legally required to act in your best interests
- Credit Representative 551883
A loan application tells the numbers. A conversation tells the story.
Your income, your assets and your debts matter, but they rarely explain the full picture. Behind the numbers there is usually a person, a family, a business, a plan, or a change nobody saw coming.
You might be:
- Buying your first home
- Looking at your next property
- Growing a portfolio
- Running your own business
- Returning to Australia
- Helping your children buy
- Refinancing
- Restructuring what you already have
- Building or renovating
- Working through a significant change in your circumstances
Your situation is specific. What you borrow should be too.
Listen. Understand. Explore. Advocate. Deliver.
Five steps. You will know where we are up to at every one of them.
-
Listen
We start with you, not with a loan. What you are trying to do, what is worrying you, what you want the next few years to look like. Twenty to thirty minutes, and I ask a lot of questions.
-
Understand
I look at the whole picture: your circumstances, your goals, your timing and the parts that do not fit a standard assessment. This is the part most applications skip.
-
Explore
With access to a broad panel of lenders, I work out which pathways are actually worth exploring for you, and which ones look good on paper and fall over in practice. Usually within about seven days of having your documents.
-
Advocate
I put your case to the lender properly, in your words and with the context that matters, and I work with your accountant, adviser or solicitor where that helps. This is the part that changes outcomes.
-
Deliver
I take ownership of the process, keep you informed and keep it moving through to settlement. Most clients have approval and a settlement date within about 30 days, depending on the lender and how fast documents come through.
And I stay available after settlement. Rates move, circumstances change, and the next move is usually easier when someone already knows your history.
Some situations need more than a standard answer
A lot of good borrowers get a no from a bank simply because their situation does not fit a template. That is usually where I am most useful.
Self-employed and business owners
Your financial picture may not fit neatly into a standard lending assessment. Two good years of trading can still read badly on the wrong form, with the wrong lender.
Property investors
As a portfolio grows, structure starts to matter more than rate. I look at how this loan affects the next one, not just this purchase.
Established property owners
You have built something. The question is usually what to do with the equity, and what it costs you to find out.
Family and intergenerational property
Helping your children into a property can be done several ways, and they are not equal. Worth understanding the options before anyone signs anything.
International and returning Australians
Income in another currency, an offshore employer or assets in two countries narrows the lender list. It does not close it.
Life and financial transitions
Separation, illness, a business change, an inheritance. When the circumstances change, so do the lending options, in both directions.
Whatever the situation, it starts the same way. A conversation.
Why use a broker instead of going straight to a bank
A bank can only offer you its own products. A broker compares across a panel of lenders and, since 2021, is legally required to act in your best interests. Your bank is not.
In most cases you do not pay for my service. Lenders pay a commission when a loan settles, and I will set out exactly what that is in writing before we go anywhere near an application. If a fee ever applies to your situation, you will get a Credit Quote first, before I do any work.
What I believe about lending
- Good lending advice starts with listening.
- Communication should make finance easier to understand, not harder.
- You deserve someone who will argue your case, not just submit it.
- Process matters. The right outcome takes more than lodging an application.
- The relationship should not end when the loan settles.
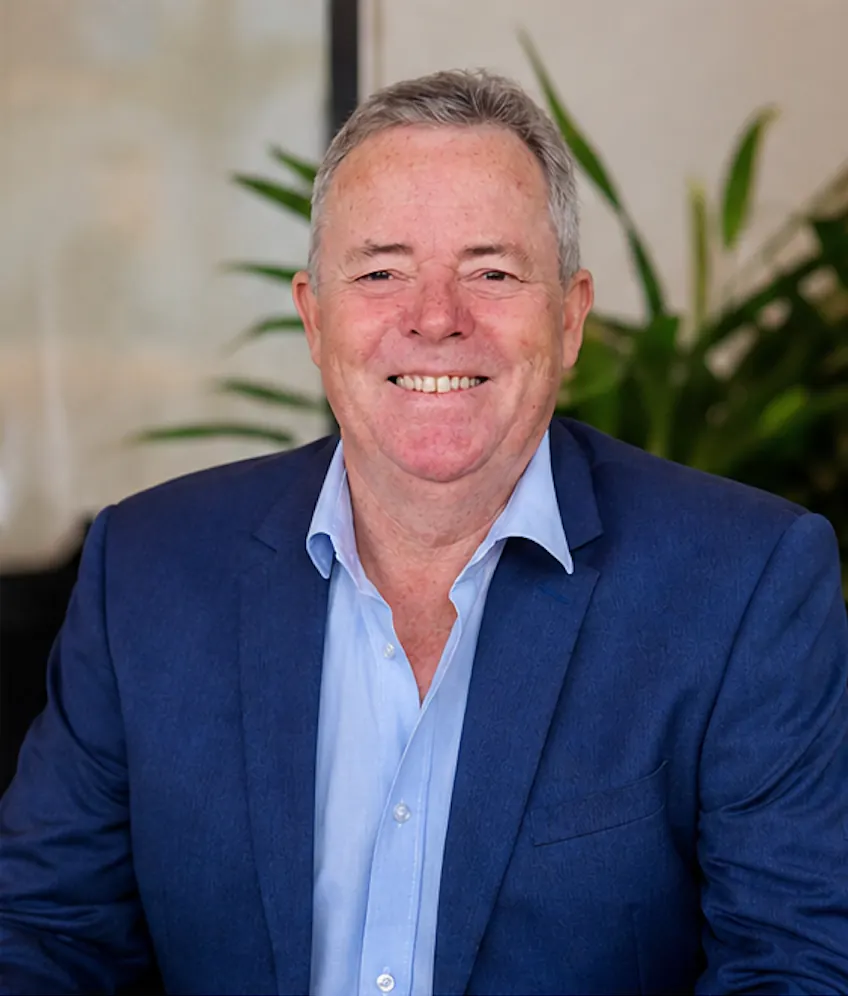
Meet Paul
Banking experience. Broking expertise. A business background. A very human approach.
Over the past six years, in home lending inside a bank and then as a broker, I have helped hundreds of Australians work through their situations and their goals. Before financial services I spent years in business, operations and client-facing roles, in Australia and overseas.
What I have enjoyed most across all of it is working with people, and understanding not just what someone is asking for but what they are actually trying to achieve. That matters more in finance than in most fields, because a loan application only ever tells part of the story.
Communication is my strongest suit. I like making complicated situations easier to understand, keeping people informed, and getting clients, lenders and other advisers on the same page about what needs to happen. And I take ownership. Good service is not just finding a solution, it is staying involved until that solution becomes an outcome.
- Two and a half years, bank home lending
- Three years, mortgage broking
- International business and operations background
- Credit Representative 551883, Purple Circle Financial Services
For me, broking is about understanding the person behind the numbers and helping them work out what comes next.
Better outcomes rarely happen in isolation
I work alongside the professionals already around you: your accountant, your financial adviser, your solicitor, your buyer's agent. If you do not have someone you need, I can usually point you to someone good.
I do not compete with your advisers. I work with them, because a lending decision made without the tax, legal or structural context is a decision made with half the information.
More possibilities. One relationship.
Through my network I have access to more than 30 lenders. The number matters because it means more possibilities. The useful part is knowing which of those possibilities are worth exploring for you.
- Home loans, including first home buyers
- Investment property loans
- Refinancing
- Construction and renovation loans
- Self-employed and business lending
- Complex and non-standard lending
- Commercial property finance
- Self-managed super fund (SMSF) lending
- Specialist lending
Not sure which one you are? That is a normal place to start.
Start a conversation
Pick a time that suits you. Answer a few quick questions so I can come to the call prepared, and I will call you then. No assumptions, no pressure, no paperwork before we have spoken.
Your details are used to prepare for and make this call, nothing else.
Prefer to just talk?
Call me on 0408 474 647. If I'm on a call I will ring you back the same day.
Or pick a time in my calendar, on Zoom or by phone.
Questions people ask before they call
In most cases, no. Lenders pay a commission when a loan settles, so my service usually costs you nothing. If a fee ever applies to your situation I will give you a Credit Quote in writing before I do any work, so there are no surprises.
Usually, for one clear reason: a broker compares across many lenders and is legally required to act in your best interests. A bank can only sell its own products and carries no such duty. You also deal with one person from the first conversation to settlement, rather than a call centre.
No. I am based in Bondi Junction and work with clients right across Australia by phone and video. Documents are signed electronically and lenders do not care where your broker sits.
Everything from a first home purchase to a portfolio restructure. I am most useful where a situation does not fit a standard template: self-employed income, an offshore employer, a family arrangement, a business change, or a life event that has moved the goalposts.
Usually yes, though it depends on how long you have been trading and how your income is documented. Different lenders assess self-employed income very differently, and the same set of financials can get a no from one and a yes from another. That is exactly the sort of thing worth a conversation before you apply anywhere.
Often yes. Foreign income, an offshore employer or assets in another country narrow the list of lenders willing to look at it, but they do not close it. The details matter a lot here, so it is worth talking it through rather than guessing from a website.
Typically I have a lender and a structure recommended within about seven days of receiving your documents, and most clients have approval and a settlement date within about 30 days after that. It depends on the lender and how quickly paperwork moves, so I will give you a realistic timeline on the first call.
It depends on the lender and the loan. As a rule of thumb, 20% avoids lenders mortgage insurance, and many lenders will go to 5% or 10% with insurance or under a government scheme. If you are a first home buyer, the First Home Guarantee may let you buy with a 5% deposit and no insurance. I will tell you which of these actually applies to you.
Eligibility depends on your income, the property price cap for your area, your residency and whether you have owned property before. The rules change from time to time, so rather than guess from a website, tell me your situation on the first call and I will check the current criteria against it.
Refinance if it leaves you ahead after the costs of switching, and not otherwise. If your loan has not been reviewed in two years it is worth a look. I will compare what you are on against the market, include the exit and setup costs, and tell you plainly if staying put is the better outcome.
Lenders pay an upfront commission when your loan settles, and usually a smaller ongoing trail commission while the loan stays with them. I will disclose the exact figures for your loan in writing before you commit. My Credit Guide explains this in full, and you get a copy before we start.
We talk about you, not about products. What you are doing, what your income and debts look like, and what you want the next few years to look like. Twenty to thirty minutes. By the end you will know what is realistic and what the next step is, and there is no obligation to go any further.
Not sure how to approach your situation?
Let's start with a conversation. No assumptions, no pressure. Just a discussion about where you are and where you want to go.
Your circumstances will change. Your plans will change. Your family may grow, your business may grow, your goals will move. I would like to be the person you call when you are ready for the next move.
Finance for what's next.
Australia wide. A more personal approach.